Home Loan Interest Rates 2026: Compare SBI, HDFC, PNB, LIC & Other Banks Before Choosing a Home Loan
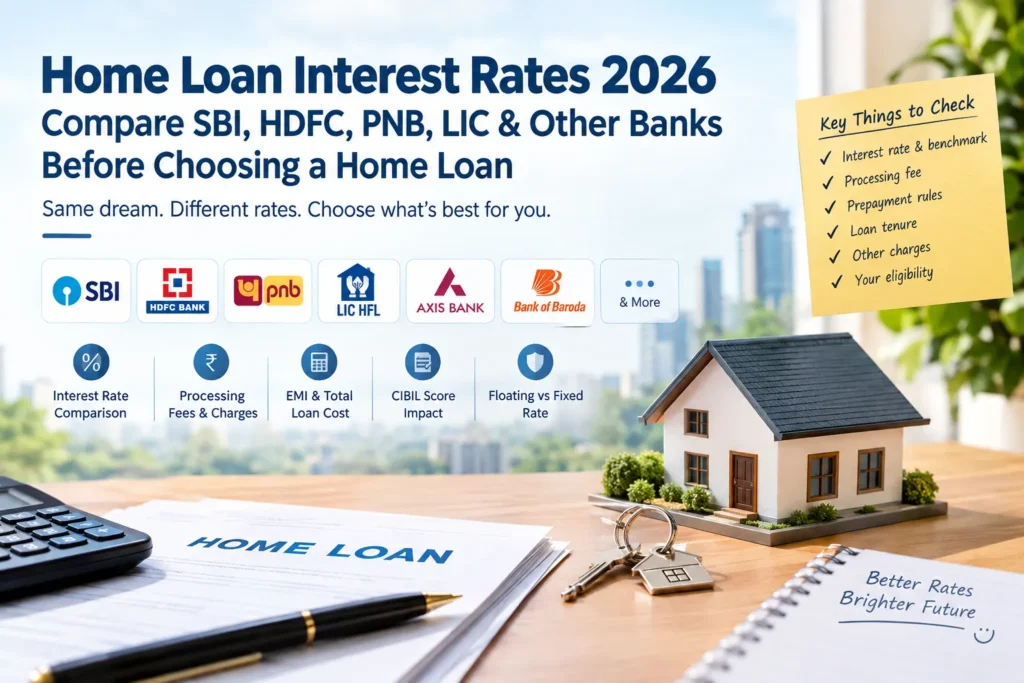
Buying a home is a major financial decision. For most buyers, the home loan interest rate is one of the biggest factors affecting the total cost of the property. In 2026, home buyers can compare loan options from lenders such as SBI, HDFC Bank, PNB, LIC Housing Finance, Axis Bank, Bank of Baroda and other housing finance companies. However, choosing a home loan is not only about finding the lowest advertised rate. Your CIBIL score, income, loan amount, property value, loan tenure, employment profile and lender charges can all affect the final offer. This guide explains how to compare home loan interest rates in 2026 and what you should check before choosing a lender. Home Loan Interest Rates 2026 — Quick Overview Home loan rates are not always the same for every customer. For example, SBI currently displays home-loan interest rates starting from 7.25% p.a., subject to its terms and conditions. HDFC states that its home-loan pricing depends on factors including the borrower’s credit profile, income, loan amount, employment category and property type. PNB’s published housing-loan pricing also varies according to factors such as CIBIL score and loan-to-value ratio. Therefore, the rate shown in an advertisement should be treated as a starting or indicative rate, not as a guaranteed rate for every applicant. SBI vs HDFC vs PNB vs LIC vs Axis vs Bank of Baroda Instead of looking only at the headline interest rate, compare the complete loan offer. Lender What to Compare Important Factor SBI Starting rate, benchmark and borrower profile CIBIL, loan amount and profile HDFC Bank Rate structure and repayment options Income, credit profile and property PNB Floating-rate options and CIBIL-linked pricing CIBIL and LTV LIC Housing Finance Rate, tenure and eligibility Income and credit profile Axis Bank Interest rate and applicable charges Credit profile and loan value Bank of Baroda Rate structure and spread CIBIL, loan limit and borrower type Important: Interest rates change from time to time. The actual rate offered to a borrower can be different from the starting rate shown publicly. For example, Bank of Baroda states that its home-loan interest pricing depends on factors such as loan limit and CIBIL score. Why the Lowest Interest Rate Is Not Always the Cheapest Home Loan This is one of the most important things to understand before applying. Suppose one lender offers you a slightly lower interest rate but charges higher fees, while another lender offers a slightly higher rate with lower charges and better repayment flexibility. The lower advertised rate may not automatically mean the lower overall cost. Before accepting an offer, check: This gives you a much clearer picture of the actual cost. How Your CIBIL Score Can Affect Home Loan Interest Rates Your credit history can have a major role in loan pricing. A strong credit profile can make it easier to qualify for competitive rates. On the other hand, a lower credit score may result in a higher rate or stricter lending conditions. PNB’s published rate structure, for example, shows different floating rates for different CIBIL-score bands. Before applying for a home loan: Check Your CIBIL Score Review your credit report for: Correcting errors before applying can help you present a stronger credit profile. Floating vs Fixed Home Loan Interest Rate Another important comparison is the type of interest rate. Floating Interest Rate A floating rate can change during the loan period based on the applicable benchmark and lender’s pricing structure. This means your EMI or loan tenure can change when the interest rate changes. RBI rules require banks to link floating-rate retail loans to an external benchmark, and the benchmark reset mechanism forms part of the loan terms. Fixed Interest Rate A fixed-rate loan is designed to provide greater certainty about the interest rate for the applicable fixed period or structure. However, the exact terms can vary by lender and product. Which One Should You Compare? Do not compare only: 7.5% vs 8.0% Also compare: benchmark + spread + reset frequency + fees + repayment conditions. That gives you a more meaningful comparison. How RBI Repo Rate Changes Can Affect Home Loans The RBI policy rate can influence the pricing of many floating-rate loans. When a loan is linked to an external benchmark, a change in the benchmark can eventually affect the borrower’s interest rate according to the applicable reset mechanism. The RBI’s framework states that floating-rate retail loans are linked to external benchmarks, with reset periods forming part of the lending arrangement. This is why home buyers should understand how their loan is benchmarked, rather than looking only at the initial interest rate. Home Loan Interest Rate Comparison Example Let’s understand the impact with a simple example. Suppose you borrow: Loan Amount: ₹50 lakhTenure: 20 years Now imagine two different interest rates: Option A: 7.5%Option B: 8.0% Even a difference of 0.50% can affect the monthly EMI and the total interest paid over a long tenure. The exact saving will depend on the lender’s calculation method, rate changes, tenure and repayment schedule. That is why it is useful to compare the complete repayment cost, rather than just the rate displayed on a bank’s website. What Is a Good Home Loan Interest Rate in 2026? There is no single rate that is automatically suitable for every borrower. A competitive rate for one customer may not be available to another customer. The final offer can depend on: For example, HDFC states that its home-loan rates depend on factors including income, credit profile, employment category, property type and loan value. So, instead of asking only “Which bank has the lowest home loan rate?”, ask: “Which lender is offering me the best overall loan structure for my profile?” Home Loan Interest Rate vs EMI Interest rate and EMI are closely connected, but they are not the same thing. Your EMI depends mainly on: A longer tenure can reduce the monthly EMI, but it can also increase the total interest paid over the life of the loan. For this reason, buyers should